Biweekly mortgage calculator

Page updated . Source-review dates are listed separately.

See how much interest and time you save by paying half your mortgage payment every two weeks.

Content updated October 30, 2026 Formula & assumptions explained
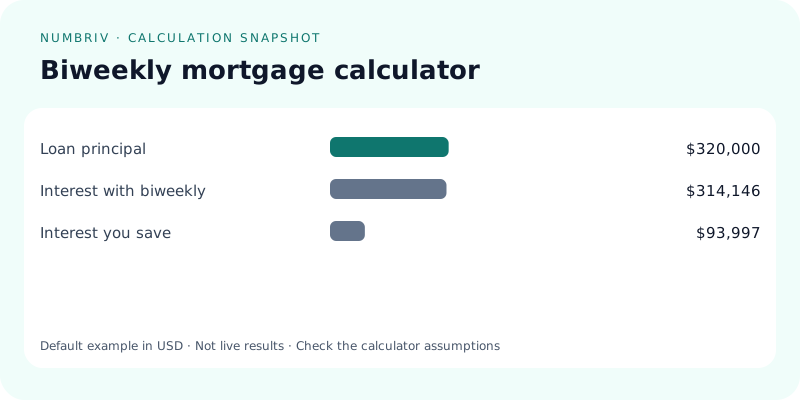
Default Biweekly mortgage calculator scenario showing Loan principal $320,000, Interest with biweekly $314,146, Interest you save $93,997
Illustrative default scenario in USD. Your inputs change the results below.

Your mortgage

$
%
Loan term
Pay every two weeks
$1,011
You'll be mortgage-free 5 yr 10 mo sooner and save $93,997
Loan principal: $320,000Interest with biweekly: $314,146Interest you save: $93,997Time saved5y 10m
  • Loan principal$320,000
  • Interest with biweekly$314,146
  • Interest you save$93,997
Interest saved$93,997
Monthly plan payoffSep 2056
Biweekly payoffNov 2050

Monthly vs biweekly balance

Biweekly payments add up to one extra monthly payment each year, which goes straight to principal.

$0$80k$160k$240k$320kStartYr 5Yr 10Yr 15Yr 20Yr 25Yr 30
Monthly paymentsBiweekly payments

How biweekly payments work

Instead of one full payment each month, you pay half every two weeks. There are 52 weeks in a year, so that's 26 half-payments, or 13 full payments instead of 12. The extra payment goes entirely to principal, which shortens your loan and cuts the interest you pay.

The formula

Biweekly payment = Monthly payment ÷ 2, paid 26 times a year

Interest is calculated on the lower balance after each payment, so savings build over time.

Example calculation

A $320,000, 30-year mortgage at 6.5%:

Monthly payment
$2,022.62
Biweekly payment
$1,011.31
Time saved
5 yr 10 mo
Interest saved
$93,997

Before you switch

  • Ask your lender first. Some don't accept biweekly payments directly, and some third-party services charge fees.
  • Make sure extra money goes to principal. Confirm the lender applies it right away rather than holding it.
  • Try the simple alternative. Adding one-twelfth of your payment each month gets almost the same result.

Frequently asked questions

Is a biweekly mortgage worth it?

For most borrowers, yes, as long as there are no fees. It’s an easy way to pay one extra payment a year without noticing it much.

Does it hurt my credit?

No. As long as you pay on time, it has no negative effect on your credit score.

Should I invest the extra money instead?

It depends on your rate and goals. Paying down a 6.5% mortgage is a guaranteed 6.5% return, which is hard to beat risk-free.

Related calculators

Explore United States calculators and coverage in USD. This calculator retains its stated jurisdiction and assumptions.

Publisher, sources and review status

Published by Numbriv editorial team. Full jurisdiction/rule review is not recorded as complete. Existing formula tests do not certify every local rule.

Calculation and editorial methodology · Tax-rule review log · Report a correction · Advertising disclosure

Model assumptions and further reading

The comparison assumes each half-payment is applied immediately and interest accrues at the annual nominal rate divided by 26. A servicer may instead hold partial payments or follow daily accrual rules. Confirm payment application and fees before treating the modeled savings as achievable.