Retirement calculator

Page updated . Source-review dates are listed separately.

Estimate your retirement savings in today’s dollars and see whether you’re on track for the income you want.

Content updated October 30, 2026 Formula & assumptions explained
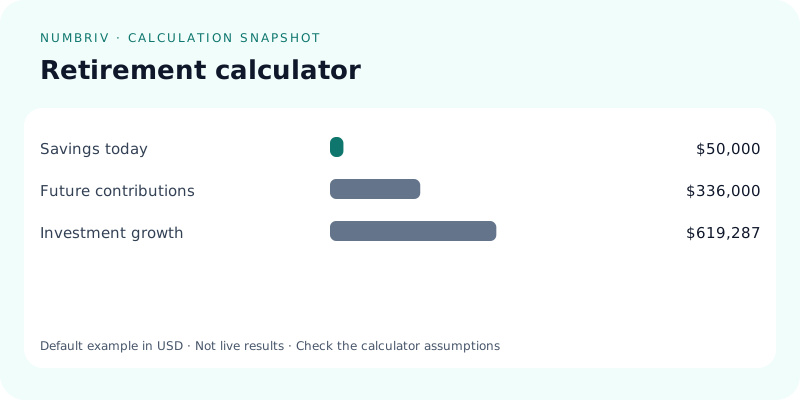
Default Retirement calculator scenario showing Savings today $50,000, Future contributions $336,000, Investment growth $619,287
Illustrative default scenario in USD. Your inputs change the results below.

Your retirement plan

years
years
$
$
%
%
$
Projected savings at 65 (today’s dollars)
$1,005,287
About $3,351 a month, 67% of your $5,000 goal
Savings today: $50,000Future contributions: $336,000Investment growth: $619,287Goal reached67%
  • Savings today$50,000
  • Future contributions$336,000
  • Investment growth$619,287
Target nest egg$1,500,000
Income (4% rule)$3,351/mo
Save instead$1,307/mo

Savings vs your target

To close the gap, save about $507 more each month.

$0$375k$750k$1.1M$1.5MStartYr 10Yr 20Yr 30
Target nest eggProjected savings

How this calculator works

This calculator grows your current savings and monthly contributions until retirement, using the inflation-adjusted return (1 + nominal return) ÷ (1 + inflation) − 1. That's why results are in today's dollars: $1 million in 35 years won't buy what $1 million buys now.

Monthly contributions are modeled as constant amounts in today’s dollars, so their nominal value must rise with inflation. A fixed nominal contribution would buy less over time and can produce a lower real balance. Your target uses a simplified 4% initial-withdrawal assumption: about 25 times desired annual income. This is a planning heuristic, not a guaranteed sustainable withdrawal rate; taxes, fees, changing returns and sequence-of-returns risk are excluded.

The formula

Real return = (1 + return) ÷ (1 + inflation) − 1
Target = Monthly income × 12 ÷ 0.04

Example calculation

You're 30, have $50,000 saved, add $800 a month, expect 7% returns with 2.5% inflation, and want $5,000 a month at 65.

Target nest egg
$1,500,000
Monthly income (4% rule)
$3,351
Contribution needed to hit target
$1,307/mo
Projected savings at 65
$1,005,287

Ways to catch up

  • Get the full employer match. It's an instant 50% to 100% return on your money.
  • Raise contributions by 1% a year. Small annual increases add up without hurting your budget.
  • Use catch-up contributions after 50. The IRS allows extra contributions to 401(k)s and IRAs.
  • Work a little longer. Each extra year adds savings, adds growth and shortens retirement.

Frequently asked questions

How much do I need to retire?

A common guide is 25 times your yearly spending in retirement. The right number depends on Social Security, pensions and your lifestyle.

Does this include Social Security?

No. Subtract your expected Social Security benefit from your income goal for a more accurate target.

What return should I assume?

Many planners use 6% to 7% for a stock-heavy portfolio and lower for conservative ones. Returns aren’t guaranteed.

Related calculators

Explore United States calculators and coverage in USD. This calculator retains its stated jurisdiction and assumptions.

Guides for this calculation

Browse every category

Publisher, sources and review status

Published by Numbriv editorial team. Full jurisdiction/rule review is not recorded as complete. Existing formula tests do not certify every local rule.

Calculation and editorial methodology · Tax-rule review log · Report a correction · Advertising disclosure

How do I account for inflation in retirement planning?

Choose a retirement spending goal in today’s money, then use an inflation-adjusted return to compare it with projected savings. Real return = (1 + nominal return) ÷ (1 + inflation) − 1. A hypothetical 6% nominal return with 3% inflation is about 2.91% real return. Keep both your income target and results in the same purchasing-power terms.

How do I plan for inflation in retirement?

Run several inflation scenarios rather than relying on one forecast. For illustration, $3,000 of monthly spending today would require about $5,418 in 20 years at constant 3% annual inflation: $3,000 × 1.03^20. This is a scenario, not a forecast. Review your spending and assumptions over time; healthcare and housing may rise differently from average prices.

Should I add inflation again to this calculator’s result?

The retirement calculator presents inflation-adjusted results in today’s dollars. Compare those results with a spending goal expressed in today’s dollars. Inflating that target again would mix future dollars with today’s purchasing power. See the assumptions above, including the simplified withdrawal-rate target.

Read the retirement income and inflation guide

Answer content updated October 27, 2026. Calculator rule-review status remains listed above.