Compound interest calculator

Page updated . Source-review dates are listed separately.

See how your savings grow over time with regular monthly contributions and compound interest.

Content updated October 30, 2026 Formula & assumptions explained
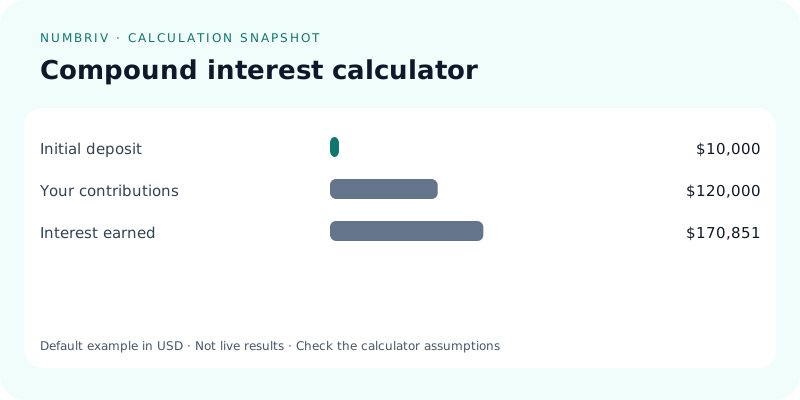
Default Compound interest calculator scenario showing Initial deposit $10,000, Your contributions $120,000, Interest earned $170,851
Illustrative default scenario in USD. Your inputs change the results below.

Your savings plan

$
$
%
years
Compounding
Balance after 20 years
$300,851
Growing at 7% a year, compounded monthly
Initial deposit: $10,000Your contributions: $120,000Interest earned: $170,851Growth share57%
  • Initial deposit$10,000
  • Your contributions$120,000
  • Interest earned$170,851
Total contributed$130,000
Interest earned$170,851
Income at 4% rule$1,003/mo

Growth over time

Your money earns $170,851 in interest, 131% on top of what you put in.

$0$75k$150k$226k$301kStartYr 5Yr 10Yr 15Yr 20
Total balanceMoney you put in

How compound interest works

With compound interest, you earn interest on your original money and on the interest it has already earned. Each year your balance grows a little faster than the year before. Over long periods, the interest can end up larger than everything you contributed.

This calculator adds your monthly contribution at the end of each month and applies your chosen compounding frequency, converted to an equivalent monthly rate.

The formula

A = P(1 + r/n)nt + PMT × [((1 + i)m − 1) ÷ i]

P is your initial deposit, r the annual rate, n the compounding periods per year and t the years. The second part adds monthly contributions (PMT), where i is the equivalent monthly rate and m the number of months.

Example calculation

You start with $10,000 and add $500 a month for 20 years at 7%, compounded monthly.

Total contributed
$130,000.00
Interest earned
$170,850.72
Final balance
$300,850.72

More than half the final balance is interest. That's the power of starting early.

Tips for faster growth

  • Start now. Ten extra years matters more than a slightly higher return.
  • Automate contributions. A fixed transfer on payday makes saving effortless.
  • Watch fees. A 1% annual fee can consume a large share of your growth over decades.
  • Use tax-advantaged accounts. A 401(k) or IRA lets more of your interest keep compounding.

Frequently asked questions

What's the Rule of 72?

Divide 72 by your interest rate to estimate how many years it takes to double your money. At 7%, money doubles in about 10 years.

Does this account for inflation?

No. To see results in today's dollars, subtract expected inflation (around 2% to 3%) from your interest rate.

What is the 4% rule?

It's a guideline suggesting you can withdraw about 4% of your savings each year in retirement with a low risk of running out. It's a starting point, not a guarantee.

Related calculators

Find planning tools by country and currency. General formulas do not apply local tax or product rules.

Guides for this calculation

Browse every category

Publisher, sources and review status

Published by Numbriv editorial team. Full jurisdiction/rule review is not recorded as complete. Existing formula tests do not certify every local rule.

Calculation and editorial methodology · Tax-rule review log · Report a correction · Advertising disclosure

Model assumptions and further reading

The annual input is a nominal rate with the selected compounding frequency, converted to a monthly equivalent. Contributions arrive at month-end. The projection assumes a constant rate and excludes fees, tax and inflation; it is not a forecast of investment returns.